Maximising Savings with the ENTERTAINER App: A Week of Delicious Deals in Singapore

As a finance and lifestyle blogger here in Singapore, I’m always on the lookout for ways to enjoy the city’s best offerings without breaking the bank. One tool that has truly transformed my dining and entertainment experiences is the ENTERTAINER app. With its extensive range of 1-for-1 deals and discounts across restaurants, cafes, and lifestyle venues, it’s a game-changer for savvy savers like me.

What is the ENTERTAINER App?
The ENTERTAINER app is a digital membership that offers exclusive 1-for-1 deals and discounts at numerous merchants in Singapore. It’s incredibly user-friendly—simply browse the deals, search by location or category, and redeem instantly. One of my favourite features is the map search function, which helps me find nearby deals effortlessly—perfect for spontaneous outings or planned dinners. You can check out their website here: https://www.theentertainerme.com/ where you can see all the great merchants they work with! Recently, the price has been reduced: It’s only $72. So essentially you could save double what I “paid” for it!

Deals Available & What I Love About the App
From local hawker-style eateries to fine dining restaurants, the app covers a wide spectrum. I love how the app not only provides great discounts but also allows me to try new places I might not have considered before. Plus, most merchants are familiar with how to use the app, making redemption seamless.

A Week of Savings in Singapore
Here’s a quick rundown of my experience this week using the ENTERTAINER app:

Monday:

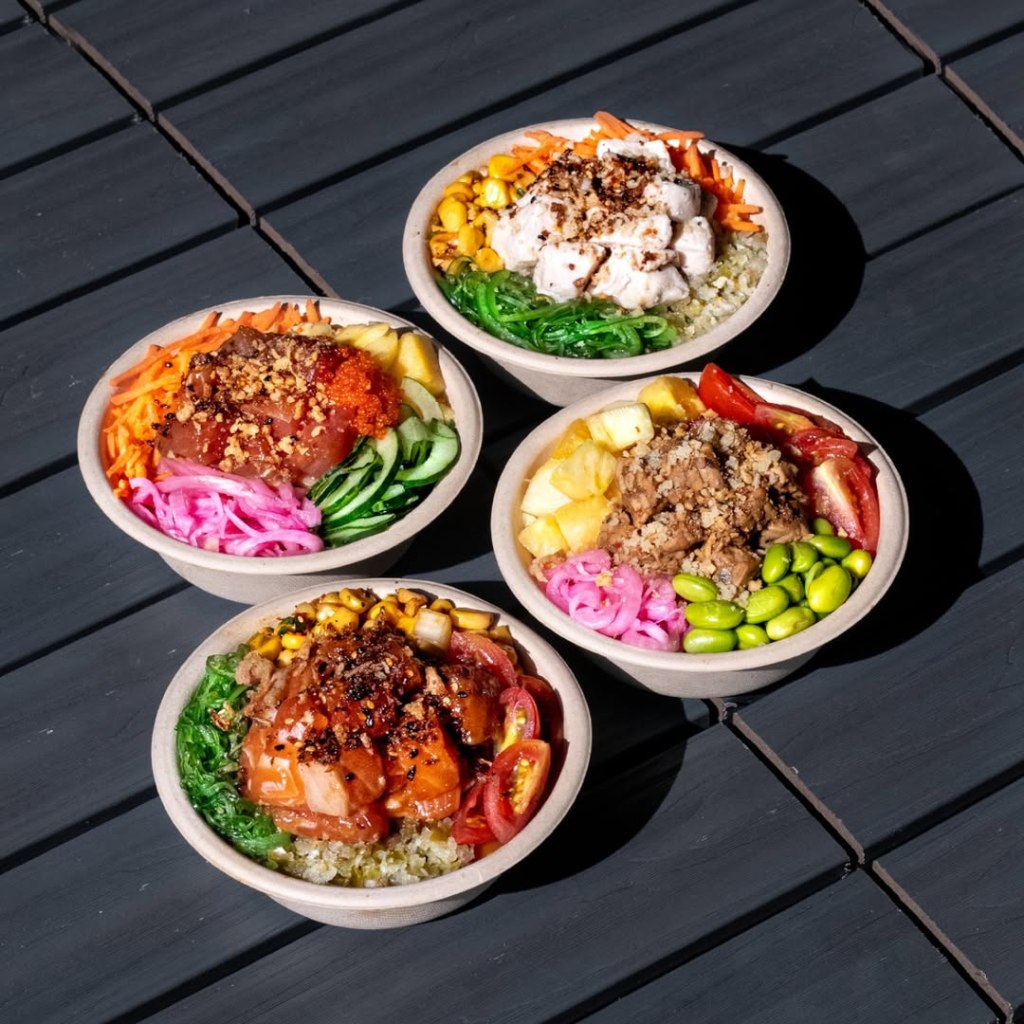
  • Poke Theory at Raffles Place
    BYO Pokebowl (Tuna, Chicken, Tempeh) at SGD 17.50 each. I shared this with a colleague, so we split the cost—saving half.
Tuesday:

  • Poke Theory again
    This time, with a drink included, the bowl still at SGD 17.50, plus an additional deal for 1-for-1 mains at Sichuan Alley, Telok Ayer. My friend and I enjoyed home-style mashed pea noodles and braised pork rib noodles. The total bill was SGD 28, but with the deal, I got the cheaper dish free—saving SGD 13.80. I also noticed Sichuan Alley offers cocktail deals through the app, which I’m eager to try next!

Wednesday:

  • Dinner at Harry’s, Boat Quay
    A 1-for-1 mains deal meant I enjoyed a delicious salmon dish while my client had chicken. Total savings: SGD 21.83.

Thursday:

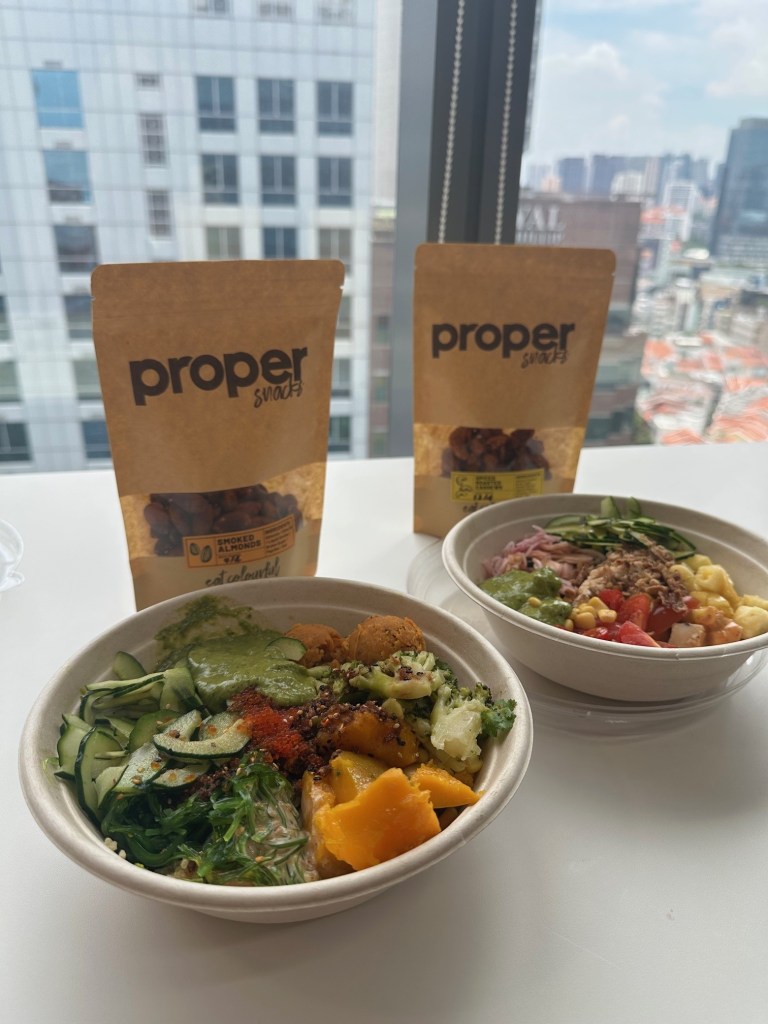
  • Back to Poke Theory
    This time, I added a snack pack of almonds (my colleague got cashews). Over three visits, I saved a total of SGD 57.13—amazing value for consistent dining!
Friday:

  • Quentin’s The Eurasian Restaurant, Ceylon Road
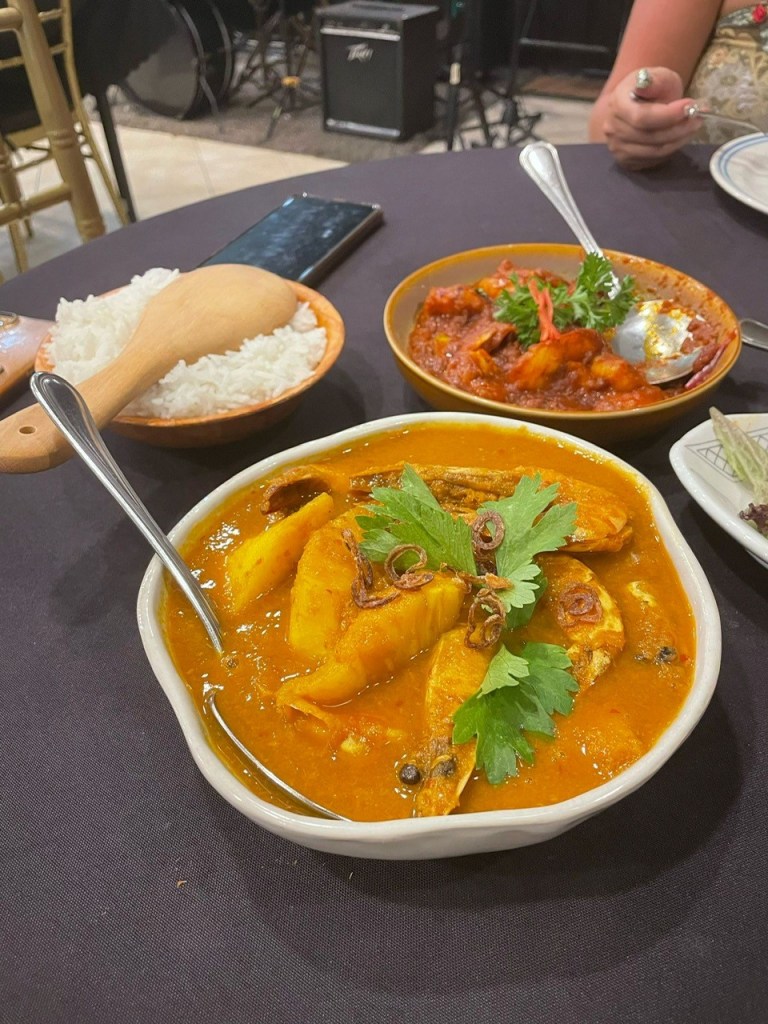
    My husband and I tried this place on a whim as it was a different cuisine that we both hadn’t had in a long time. We ordered several dishes—prawn curry, fish bostador, and a meaty cutlet—some under the 1-for-1 mains deal. Our total savings: SGD 28.02. The food was fantastic, and I didn’t expect such a feast!
Sunday:

  • Stirling Steaks, East Coast Road
    I am normally not in the mood for ‘western food’, but my husband & I decided that we will go on the hunt for a really good steak! Both of us enjoyed perfectly cooked sirloin steaks with fries and a garden salad. Total savings here: SGD 21.83. The steak was so good—I can’t wait to go back! I also noticed that they do a steak buffet & have a speakeasy upstairs, so that would be cool to try.

Total Savings for the Week: SGD 148.46

Why I Recommend the ENTERTAINER App
This week’s experience highlights how easy and rewarding using the ENTERTAINER app can be. It complements my previous posts about saving money in Singapore, proving that with a little planning, you can enjoy a variety of amazing places while keeping your budget in check. The app’s user-friendly interface and the familiarity of merchants with how to use it mean redemption is quick and hassle-free.

Whether you’re a foodie, a coffee lover, or someone who enjoys exploring new entertainment venues, the ENTERTAINER app makes it simple to try new places and save big. It’s a fantastic way to make the most of Singapore’s vibrant dining scene without overspending.

I haven’t even explored the other options available on the app, like massages, treatments and manicures. As a foodie, I’ve mainly been focusing on the restaurant deals, but for experiences & treatments, this app is great too!

Final Thoughts
If you’re looking to stretch your dollar and enjoy Singapore’s best offerings, I highly recommend giving the ENTERTAINER app a try. My week of savings shows just how much you can enjoy—SGD 148.46 saved in just seven days! Whether for casual meals, special date nights, or catching up with friends, this app is a must-have for any budget-conscious person in Singapore.

Happy saving and dining!

(Don’t forget: You can check out their website here: https://www.theentertainerme.com/ where you can see all the great merchants they work with! Recently, the price has been reduced: It’s only $72. So essentially you could save double what I “paid” for it!)

And I’m very excited to announce that I have a discount code – DANNI20 – for $20 off for my readers! You just need to add this promo code at checkout.

Checkout [theentertainerme.com]
Top 7 Financial Lessons For Successful Expats in Singapore

Today I’m celebrating a big milestone for me – recording & releasing 70 episodes of my podcast! It’s been an incredible ride—covering everything from investing tips to budgeting hacks, lifestyle adjustments, and breaking taboos around talking about money. I’ve loved hearing your stories, answering your questions, and seeing so many of you take confident steps towards financial independence. To celebrate this milestone, here are my top 7 lessons I’ve learned from working with amazing expats:

1. Start with Budgeting: Know Your Cash Flow


– Why it matters: As an expat, your income and expenses may fluctuate due to currency differences, lifestyle choices, or unexpected costs. Budgeting helps you understand where your money goes and ensures you’re living within your means.


– Practical tip:Use apps like Spendee to track your expenses in SGD and foreign currencies. Set a monthly budget for essentials, savings, and fun.


– Benefit: Clear cash flow management reduces financial stress and helps you plan for big expenses like housing, travel, or investing.


2. Invest Early and Often: Harness the Power of Time


– Why it matters: The earlier you start investing, the more you benefit from compound interest. Even small regular contributions can grow significantly over time.


– Practical tip: Consider opening an SRS (Supplementary Retirement Scheme) account or investing through ETFs, or local brokers. Set up automatic contributions to stay consistent.


– Benefit: Building wealth steadily without feeling overwhelmed, even if you start with modest amounts.


3. Maximise Your Investing Environment & Benefits: Leverage Singapore’s Unique Landscape


– Why it matters: Singapore offers attractive investments, which grow tax-free and can provide a safety net for retirement. These can also be portable and move with you when you repatriate.


– Practical tip: Contribute regularly to these accounts and optimise your contributions based on your goals.


– Benefit: Long-term growth of your retirement funds with flexibility & control.


4. Break the Taboo: Talk Openly About Money


– Why it matters: Many cultures consider discussing money taboo, but open conversations lead to better financial decisions and support.


– Practical tip: Join expat or women’s financial groups, attend workshops, or have honest chats with friends or mentors about money management.


– Benefit: Increased confidence, shared knowledge, and collective empowerment to make smarter choices.


5. Diversify Your Portfolio: Don’t Put All Eggs in One Basket


– Why it matters: Relying on a single investment or income source can be risky, especially in a foreign country with currency or market fluctuations.


– Practical tip: Spread investments across stocks, bonds, and international funds. Always consider your risk tolerance & investment horizon.


– Benefit: Reduced risk and more stable growth, protecting you from market dips or currency shifts.


6. Prioritise Lifestyle & Financial Balance: Enjoy Life Responsibly


– Why it matters: Living abroad offers unique experiences, but overspending can jeopardise your financial goals.


– Practical tip: Allocate a fun budget, explore affordable local activities, and avoid impulse spending. Use cashback and discounts for expat-friendly services.


– Benefit: A fulfilling life without sacrificing your financial future, creating sustainable habits.


7. Build a Support Network: Connect with Others


– Why it matters: Sharing experiences, challenges, and successes helps you stay motivated and informed.


– Practical tip: Join expat communities, women’s finance groups, or online forums. Attend local events, webinars, or workshops.


– Benefit: Access to advice, encouragement, and opportunities that you might not find alone—plus, it makes your financial journey more enjoyable.

Thank you for being part of this amazing community. Here’s to many more episodes of learning, growing, and thriving financially—together. I invite you to visit DanielleTeboul.com for exclusive resources, and follow me on socials @expatfinances for daily tips and inspiration. And if you’ve enjoyed this journey, please leave a review or share this episode with your friends—your support means the world!

Cost of Living Comparison: Singapore vs. Other Expat Hotspots

As an expat in Singapore, it’s natural to compare the cost of living here with other popular expatriate destinations. Singapore is often lauded for its high standard of living, safety, and excellent infrastructure, but it also comes with a hefty price tag. In this article, we will analyse how Singapore’s expenses stack up against other expat hotspots like Hong Kong, Dubai, Sydney, Bali, and London. *** The Aussie dollar fluctuates constantly in comparison to SGD, so a lot of these conversions are general from AUD to SGD. When I moved to Singapore, it was one for one, but as of today, SGD 1 is equivalent to AUD 1.20.

1. Housing Costs

Singapore: Housing can be one of the most significant expenses for expats. Depending on the location and type of accommodation, monthly rents for a two-bedroom apartment can range from SGD 2,500 (although I’m seeing less on this price range) to SGD 5,000 in popular districts.

Hong Kong: Often regarded as one of the most expensive cities globally, housing in Hong Kong can be even pricier than in Singapore. A similar two-bedroom apartment in central areas can cost upwards of HKD 30,000 (approximately SGD 5,200).

Dubai: In contrast, Dubai offers more affordable housing options. A two-bedroom apartment in a desirable area may range from AED 7,000 to AED 12,000 (approx. SGD 2,400 to SGD 4,200).

Sydney: The rental market in Sydney is competitive, with costs ranging from AUD 2,500 to AUD 4,000 (approx. SGD 2,400 to SGD 4,800) for a two-bedroom apartment in the city centre.

Bali: Bali stands out as a budget-friendly option. A two-bedroom villa can be rented for as low as IDR 6,000,000 to IDR 12,000,000 (approx. SGD 570 to SGD 1,140), making it an attractive option for expats seeking affordability.

London: Housing in London can be steep, particularly in central areas where a two-bedroom apartment can range from GBP 2,500 to GBP 4,000 (approx. SGD 4,500 to SGD 7,200).

2. Transportation

Singapore: The public transport system in Singapore is efficient and affordable. A monthly use of public transport costs around SGD 120, while taxis and rideshare services are readily available.

Hong Kong: Similar to Singapore, Hong Kong has an excellent public transport system. A monthly pass costs around HKD 600 (approx. SGD 102), making it comparably priced.

Dubai: Public transport options in Dubai are limited compared to Singapore and Hong Kong, but the metro system is expanding. A monthly pass costs AED 300 (approx. SGD 110).

Sydney: Sydney’s public transport system can be expensive, with monthly costs around AUD 200 (approx. SGD 200).

Bali: Transportation in Bali is typically by scooter or car rental, with costs being relatively low. A scooter rental can average around IDR 1,000,000 (approx. SGD 95) per month.

London: The cost of public transport in London can be higher, with a monthly pass costing around GBP 150 (approx. SGD 270).

3. Groceries and Dining Out

Singapore: Grocery prices in Singapore can be higher than in many countries, with a monthly grocery bill averaging around SGD 400 to SGD 600. Dining out ranges from SGD 5 for a local meal (in local hawker centres) to SGD 100 or more for nicer restaurants or fine dining, and in the SGD 200 and above price point for buffets.

Hong Kong: Groceries can be slightly more expensive than in Singapore, averaging around HKD 3,000 (approx. SGD 510) per month. Eating out can also be pricey, with meals ranging from HKD 50 to HKD 1,000 (approx. SGD 8.50 to SGD 170).

Dubai: Grocery prices are relatively affordable, averaging around AED 800 (approx. SGD 300) per month. Dining out can vary widely, with local meals costing AED 30 (approx. SGD 11) and upscale dining ranging much higher.

Sydney: Groceries in Sydney can be similar to Singapore, costing around AUD 600 (approx. SGD 600) monthly. Dining out can be pricey, with local meals averaging AUD 25 (approx. SGD 25).

Bali: Grocery costs are significantly lower, averaging around IDR 2,000,000 (approx. SGD 190) per month. Dining out is also economical, with local meals often costing less than SGD 5.

London: Grocery prices in London can be high, with average monthly costs of GBP 300 (approx. SGD 540). Restaurant meals can range from GBP 10 to GBP 100 (approx. SGD 18 to SGD 180).

4. Healthcare

Singapore: Healthcare in Singapore is of high quality, but costs can add up. A typical health insurance plan for expats can be around SGD 3,000 to SGD 6,000 per year.

Hong Kong: Healthcare costs are comparable, with expats typically spending around HKD 30,000 (approx. SGD 5,100) annually for health insurance.

Dubai: Healthcare costs are generally lower, with health insurance averaging around AED 8,000 (approx. SGD 3,000) annually.

Sydney: Healthcare can be more expensive, with health insurance plans costing around AUD 2,000 to AUD 3,000 (approx. SGD 2,000 to SGD 3,600) yearly.

Bali: Healthcare is affordable, but quality can vary. Expat health insurance plans may range from IDR 2,000,000 to IDR 5,000,000 (approx. SGD 190 to SGD 480) annually.

London: Healthcare is often covered by the NHS for residents, but private health insurance can range from GBP 1,000 to GBP 2,000 (approx. SGD 1,800 to SGD 3,600) annually.

In conclusion, while Singapore is one of the more expensive cities for expats, it offers a unique blend of quality of life, safety, and cultural diversity. Housing costs are a significant factor, especially when compared to cities like Dubai and Bali, which offer more affordable options. Transportation and healthcare costs are relatively competitive, but groceries and dining out can add to your monthly budget.

Ultimately, the best choice for an expat depends on personal priorities, lifestyle, and financial situation. Each city has its own unique advantages, and understanding the cost of living in relation to those factors is crucial for making an informed decision.

Financial Implications of Moving Back Home: What Expats in Singapore Should Consider

Relocating back to your home country can be an exciting yet daunting prospect, especially for expats living in Singapore. Beyond the emotional aspects, it’s crucial to understand the financial implications of your move. Here’s a comprehensive guide on what to consider when planning your return, focusing on key jurisdictions like the UK, Australia, France, Germany, other parts of the EU, Southeast Asia, and India.

1. Cost of Living Adjustments

One of the first financial aspects to evaluate is the cost of living in your home country compared to Singapore. Cities like London or Sydney might have similar living costs, but factors such as housing, transportation, and utilities can vary significantly. Research the current costs in your destination to create an accurate budget.

2. Currency Exchange and Transfer Costs

Handling your finances while moving back home involves currency exchange and transfer fees. The Singapore dollar will need to be exchanged for your home currency, and fluctuating exchange rates can impact how much money you ultimately receive. Consider using money transfer services that offer competitive rates and lower fees to maximise your funds. I’ve mentioned before that I’ve used companies like OFX to handle my currency exchange, to ensure the best rates.

3. Tax Obligations

Understanding your tax obligations is crucial before returning home. Each country has different rules regarding tax residency and obligations for returning expats. For instance:

  • UK: You may be subject to tax on your worldwide income if you return and remain a tax resident.
  • Australia: Similar rules apply; if you become a resident again, you’ll be taxed on your global income.
  • France and Germany: Both countries have strict residency rules, and you may need to pay taxes on your global income.
  • Other EU countries: Tax residency rules can vary widely; it’s essential to consult with a tax advisor familiar with cross-border taxation.
  • Southeast Asia and India: Tax implications can also differ significantly in these regions. For example, India taxes global income if you meet specific residency criteria.

Tax is a huge part of financial planning; we are very lucky whilst living and working in Singapore, as taxes are low & there is no Capital Gains Tax on investments. However, that won’t always be the case upon repatriation, which is why tax planning is so important.

4. Pension Considerations

If you have been contributing to a pension scheme in Singapore, such as an SRS account, or CPF if you’ve become PR, you may wish to understand how this will be affected once you return. Some expats choose to leave their pension funds in Singapore, while others may transfer them back home. Each option has its own implications for taxation and access to funds, so seek professional advice tailored to your situation. Check out my previous content on SRS & pensions for more information on this.

5. Property Ownership and Housing Market

If you own property in your home country, consider the current housing market. Will you sell, rent, or keep your property? If you’re returning to a place where property values are fluctuating, this can significantly impact your financial situation. For example, in the UK, property prices can vary dramatically by region, while in India, urban growth might be changing property values rapidly.

6. Health Insurance and Medical Costs

Healthcare systems differ vastly from Singapore, where expats often enjoy comprehensive health insurance. In the UK, the NHS provides public healthcare, but private health insurance may be advisable. In Australia, the Medicare system is available, while in India, the private healthcare sector can be expensive without insurance. Ensure you have adequate health coverage that meets your needs upon your return.

7. Employment Opportunities

If you’re considering employment upon your return, it’s important to assess the job market in your home country. Research potential salaries and benefits, and consider how your experience in Singapore might translate into local job opportunities. Economic conditions can vary widely—Australia and Germany have robust job markets, while certain sectors in the UK and EU may be more challenging. Don’t forget to calculate how tax will impact your salary, too.

Moving back home is a significant step that requires careful financial planning. By considering cost of living, tax obligations, pension implications, housing markets, health insurance, and employment opportunities, you can navigate your return more smoothly. Consulting with financial advisers familiar with both Singaporean and your home country’s regulations can also provide valuable insights, helping you make informed decisions as you embark on this new chapter of your life.

Retiring in Singapore vs. Returning Home: Pros & Cons

As individuals approach retirement, the decision of where to spend their golden years can be both exciting and daunting. For many expatriates and locals alike, Singapore presents a unique blend of modernity, stability, and vibrant culture. However, the idea of returning to one’s home country also holds significant appeal. This article explores the pros and cons of retiring in Singapore versus returning home.

Retiring in Singapore

Pros:

  1. High Quality of Life: Singapore consistently ranks high in global quality of life indices. Its world-class healthcare system, low crime rates, and efficient public services create a safe and comfortable environment for retirees.
  2. Cultural Diversity: Singapore is a melting pot of cultures, offering a rich tapestry of experiences. Retirees can enjoy a variety of cuisines, festivals, and cultural events, allowing for an enriching lifestyle.
  3. Strong Infrastructure: The country’s efficient public transport system and well-maintained amenities make it easy for retirees to navigate and access services.
  4. Financial Stability: Singapore is known for its robust economy and stable political climate, providing a secure environment for financial investments and savings.

Cons:

  1. High Cost of Living: One of the most significant drawbacks of retiring in Singapore is the high cost of living. Housing, healthcare, and daily expenses can be steep, which may strain retirement savings.
  2. Limited Space: Singapore is a small island state with limited space, which can lead to feelings of congestion and a lack of privacy, especially in densely populated areas.
  3. Healthcare Accessibility: Although healthcare is of high quality, it can also be expensive, particularly for those without adequate health insurance.
  4. Cultural Adjustment: For expatriates returning after years abroad, adjusting to local customs and social norms might pose challenges.
  5. Visa Requirements: Generally, only expats who have converted to PR or Singapore Citizen are able to retire in Singapore.

Returning Home

Pros:

  1. Familiarity: Returning to one’s home country can provide a sense of comfort and belonging. Familiar surroundings, friends, and family can offer emotional support during retirement.
  2. Lower Cost of Living: In many cases, the cost of living in one’s home country may be significantly lower than in Singapore, allowing for a more comfortable retirement on a fixed income.
  3. Cultural Connection: Retirees can immerse themselves in their native culture, traditions, and language, fostering a sense of identity and continuity.
  4. Potential for Community Engagement: Returning home may present opportunities to engage in community activities, volunteer work, or even part-time employment, providing social interaction and purpose.

Cons:

  1. Healthcare Concerns: Depending on the country, healthcare quality and accessibility may vary greatly. Some retirees may find themselves facing inadequate healthcare systems or long wait times.
  2. Economic Instability: Certain regions may experience economic challenges, which could impact pensions, savings, and overall financial security.
  3. Social Isolation: If retirees have been away for an extended period, they may find it difficult to reconnect with old friends and adapt to changes in their home environment.
  4. Limited Infrastructure: Depending on the location, retirees may encounter challenges with transportation, utilities, and public services that are less developed than those in Singapore.

Ultimately, the decision to retire in Singapore or return home is deeply personal and influenced by various factors, including financial considerations, family ties, and lifestyle preferences. While Singapore offers a modern, vibrant environment with high-quality amenities, returning home can provide comfort, familiarity, and community connection. Prospective retirees should weigh these factors carefully to make the most informed decision for their future.

Common Investment Mistakes Expats Make in Singapore and How to Avoid Them

Singapore, known for its robust economy and strategic location in Asia, attracts a diverse expatriate community. While the city-state offers ample investment opportunities, many expats fall victim to common pitfalls that can hinder their financial growth. Understanding these mistakes and taking proactive measures can help expats make informed investment decisions.

1. Neglecting Local Tax Regulations

One of the most significant mistakes expats make is not understanding Singapore’s tax regulations. Unlike many countries, Singapore has a relatively low tax rate, but expats may still be liable for tax on income earned outside of Singapore, depending on their residency status.

How to Avoid: Consult a tax advisor who specialises in expat finances to ensure compliance and optimise your tax situation. Understanding tax treaties between Singapore and your home country can also help prevent surprises at tax time.

2. Overlooking Currency Risks

Many expats earn their salaries in foreign currencies, which can create currency risk when investing in Singaporean assets. Fluctuations in exchange rates can significantly impact the returns on investments made in local currency.

How to Avoid: Consider investing in diversified currency portfolios. It’s also wise to maintain a balanced currency exposure, ensuring that your investments are not overly reliant on the performance of a single currency.

3. Failing to Research Local Investment Options

Expats often gravitate towards familiar investment vehicles from their home countries, which may not align with Singapore’s market dynamics or regulatory environment. This can lead to missed opportunities in local markets.

How to Avoid: Take the time to research Singapore’s investment landscape. Engage with local financial advisors who understand the market and can provide insights into promising sectors, such as technology, healthcare, and real estate.

4. Rushing Into Real Estate Investments

Real estate could be seen as a good investment choice for many expats in Singapore due to its perceived stability and potential for appreciation. However, jumping into property investments without thorough research can lead to costly mistakes, especially if you have to pay 60% stamp duty!

How to Avoid: Conduct comprehensive market research and consider factors such as location, property type, and market trends. Additionally, understand the regulations around property ownership for foreigners in Singapore to avoid legal complications.

5. Ignoring Retirement Planning

Many expats focus on short-term financial goals and overlook long-term retirement planning. This can be particularly challenging in Singapore, where the Central Provident Fund (CPF) system is primarily designed for permanent residents and citizens.

How to Avoid: Start planning for retirement early, even if it seems far away. Look into investment options that cater to expats, such as international retirement accounts or overseas insurance bond plans that can provide growth and security.

Investing as an expat in Singapore offers exciting opportunities but comes with its own set of challenges. By being aware of common mistakes and implementing strategies to avoid them, expats can navigate the financial landscape more effectively. Continuous education, seeking professional advice, and maintaining a balanced approach to investments can pave the way for a financially secure future in this dynamic city-state.

UK Pensions: What Expatriates in Singapore Can and Can’t Do

As the global workforce becomes increasingly mobile, many UK nationals find themselves living and working abroad. Singapore, known for its vibrant economy and high standard of living, is a popular destination for expatriates. However, living overseas can complicate financial matters, particularly regarding pensions. If you’re a UK expat in Singapore, understanding your pension options is crucial. This article outlines what you can and can’t do with your UK pension while living in Singapore.

Understanding the Basics of UK Pensions

Before diving into the specifics for expats, it’s important to understand the types of UK pensions available:

  1. State Pension: This is a government-provided pension based on your National Insurance contributions throughout your working life.
  2. Defined Benefit (DB) Schemes: Often referred to as final salary pensions, these schemes provide a retirement income based on your salary and years of service.
  3. Defined Contribution (DC) Schemes: These are personal pensions where the amount you receive in retirement depends on how much you and your employer contribute, as well as the performance of the investments.

What You Can Do as an Expat in Singapore

  1. Claim Your State Pension: As a UK citizen, you can claim your State Pension irrespective of where you live. The amount you receive may be affected by your National Insurance contributions and any time spent living abroad. It’s essential to notify the UK government of your overseas address to ensure you receive your payments.
  2. Transfer Your Pension: If you have a Defined Contribution pension scheme, you may have the option to transfer your pension to a Qualifying Recognised Overseas Pension Scheme (QROPS). This can provide you with more flexible access to your funds and potential tax benefits. However, it’s crucial to seek professional financial advice before proceeding with a transfer, as there can be significant charges and tax implications involved.
  3. Continue Contributions: If you’re a self-employed individual or have the option to contribute to a personal pension plan while working in Singapore, you can continue to make contributions to your UK pension generally for the first five years you are living overseas. This can help maintain your retirement savings and potentially increase your eventual payout.
  4. Take Tax Benefits into Account: Depending on your residency status in Singapore, you may be entitled to certain tax allowances which could impact your pension withdrawals or contributions. It’s advisable to consult with a tax advisor to understand your obligations and opportunities. Be aware of the UK tax implications of making withdrawals from your UK pension as the UK/Singapore double tax treaty will usually mean any withdrawals you make will still be subject to UK tax.

What You Can’t Do as an Expat in Singapore

  1. Access Your Pension Early: Generally, you cannot access your UK pension funds before the age of 55, regardless of your location. Early withdrawals can incur significant tax penalties, so it’s crucial to plan ahead.
  2. Ignore Currency Risk: If you transfer your pension to a QROPS or another overseas scheme, you may expose yourself to currency risk. Fluctuations in exchange rates can impact the value of your pension, especially if it is held in a different currency.
  3. Assume Automatic Tax Relief: While living in Singapore, you may be subject to different tax laws and regulations that could affect your pension. It’s important to understand that tax relief on contributions may not apply if you’re no longer a UK resident. Consult a financial advisor to navigate these complexities.
  4. Neglect Local Regulations: Singapore has its own set of regulations regarding pensions and retirement savings (like the Central Provident Fund, CPF). Expatriates should familiarise themselves with local laws and how they interact with UK pension regulations to avoid any compliance issues.

Navigating your UK pension as an expatriate in Singapore can be complex, but understanding your options is crucial for securing your financial future. By knowing what you can and cannot do with your pension, you can make informed decisions that benefit your retirement planning. Always consider seeking advice from financial professionals experienced in both UK and Singaporean pension regulations to ensure you are making the best choices for your circumstances. With careful planning, you can enjoy the benefits of living abroad while also safeguarding your financial future.

Maximising Savings with Singapore’s Financial Opportunities: A Guide for Expats

Singapore, often regarded as a global financial hub, offers a spectrum of financial products designed to cater to both residents and expatriates. With a robust banking sector, various local banks and financial institutions provide a range of savings accounts, fixed deposits, and investment-linked products. This article aims to give expats an overview of these offerings to help maximise their savings and investment potential while living in this vibrant city-state.

Understanding the Financial Landscape in Singapore

Before diving into specific products, it’s important to understand the financial landscape in Singapore. The Monetary Authority of Singapore (MAS) regulates the country’s banks and financial institutions, ensuring a safe and stable environment for investors. Expats are often eligible for the same products as Singaporean citizens, allowing them to take full advantage of the financial services available. One thing that is very important to understand whilst looking at financial products in Singapore, is understanding the regulations, and the tax implications involved if you were to move abroad.

Savings Accounts

1. High-Interest Savings Accounts

Many local banks offer high-interest savings accounts specifically designed to attract depositors looking for better returns on their savings. For instance:

  • DBS Multiplier Account: This account offers tiered interest rates that increase based on the account holder’s monthly transactions, which could include salary credits, investments, and insurance premiums. It’s ideal for expats looking to consolidate their banking activities and earn higher interest.
  • OCBC 360 Account: Similar to DBS, the OCBC 360 Account provides various ways to earn bonus interest rates. Expats can benefit from higher rates by meeting certain criteria, such as making regular deposits or using their credit cards.

2. Joint Accounts

For expat couples, joint savings accounts can be a practical way to manage household finances. Many banks offer joint accounts with competitive interest rates, making it easier for partners to save together while enjoying the benefits of compounded interest.

Fixed Deposits

Fixed deposits (FDs) are a popular option for expats seeking secure and guaranteed returns. These accounts require users to commit their funds for a fixed term, during which the interest rate remains constant.

1. Standard Fixed Deposit Accounts

Most local banks, including UOB, Maybank, and HSBC, offer fixed deposit accounts with varying tenures, typically ranging from one month to several years. The interest rates for FDs are generally higher than traditional savings accounts, making them an attractive option for expats looking to grow their savings without exposure to market risks. However, this is not a stable long-term financial plan, and should only be used for short-term.

2. Foreign Currency Fixed Deposits

For expats earning in foreign currencies, foreign currency fixed deposits can be advantageous. They allow individuals to hold deposits in their home currency while potentially benefiting from favorable interest rates and currency fluctuations. Banks such as Citibank and Standard Chartered offer these products, which can be tailored to the specific needs of expats. It’s important to remember that there will always be currency risk when dealing in FX (foreign exchange),so be mindful of this when looking at the FD returns.

Investment-Linked Products

For those looking to go beyond traditional savings and fixed deposits, investment-linked products provide a way to grow wealth through market exposure while enjoying some insurance benefits.

1. Endowment Plans

Many insurance companies in Singapore offer endowment plans that combine savings and insurance protection. These plans typically have a fixed maturity period and offer guaranteed returns, making them appealing to people who want a low-risk investment option. However, I always say that if a product offers ‘guaranteed returns’, it’s guaranteed that you will lose out! These products’ returns are very low, sometimes between 1-3%, which most of the time will not even battle inflation. While they are suitable for those who are very risk adverse, they are not a very stable way to generate long-term returns, as you could (most probably will) be missing out on potential upside, that you could have gotten from other investments.

2. Unit Trusts

Unit trusts are collective investment schemes that pool money from multiple investors to invest in diversified portfolios. These cater to different risk appetites, from conservative to aggressive. Expats can leverage these products to diversify their investment portfolios and potentially achieve higher returns over the long term. Many of these will have insurance wrappers, that don’t really offer a tonne of coverage, but means that: 1. your loved ones will receive the gains when you pass on & 2. they may be classed as a tax-efficient product in various jurisdictions.

Maximising savings while living in Singapore involves understanding and utilising the diverse range of financial products available. From high-interest savings accounts to fixed deposits and investment-linked products, expats have numerous options to grow their wealth. It’s essential to assess individual financial goals, risk tolerance, and investment horizon when choosing the right financial products.

Before making any decisions, expats should consider consulting with a financial advisor to tailor a savings and investment strategy that aligns with their unique circumstances. With the right approach, expats can effectively navigate Singapore’s financial landscape and maximise their savings for a secure financial future.

Adapting Your Financial Goals as an Expat in Singapore

Living as an expatriate in Singapore offers a wealth of opportunities, from a thriving job market to a vibrant cultural scene. However, it also presents unique financial challenges that require continuous reassessment and realignment of your financial goals. As a wealth manager in Singapore, I understand the importance of adapting your financial strategy to ensure it aligns with your evolving circumstances. Here are some key considerations for expats looking to realign their financial goals after several years in this dynamic city-state.

1. Evaluate Your Current Financial Position

Before setting new financial goals, it’s essential to assess your current financial standing. Take stock of your income, expenses, savings, and investments. Consider how your financial situation has changed since you first arrived in Singapore. Factors such as salary adjustments, changes in living costs, and shifts in your personal circumstances (e.g., marriage, children, or returning to your home country) can significantly impact your financial landscape. Have you already achieved some of the financial goals that you have previously set? Or do you need to reevaluate those, too?

2. Understand the Cost of Living

Singapore is known for its high cost of living, which can fluctuate due to various economic factors. Reassess your budget to ensure it reflects your current lifestyle and expenses. This includes housing, education, healthcare, and daily living costs. It’s crucial to account for potential changes in these areas, especially if you plan to stay long-term or if your family situation evolves. Singapore is not the same place it once was; rent has fluctuated massively since I moved here, as have school fees, insurance costs & groceries.

3. Revisit Your Investment Strategy

Market conditions and personal risk tolerance can change over time. Take the opportunity to review your investment portfolio to ensure it aligns with your current financial goals. Consider diversifying your investments to mitigate risk and capitalise on new opportunities. If you’re planning to stay in Singapore for the long term, you may want to explore local investment options, such as real estate (depending on your nationality or PR status) or Singapore-based mutual funds, which can sometimes be tax-efficient in other jurisdictions.

4. Plan for Retirement and Long-Term Goals

As an expat, your retirement planning may look different than that of locals. Reassess your retirement goals and ensure that your savings plan is on track. Consider factors such as your desired retirement age, lifestyle expectations, and potential repatriation. Additionally, familiarise yourself with Singapore’s Central Provident Fund (CPF) system and any tax implications related to your home country. You may have gained Permanent Residency in the time that you have been here, and therefore need to factor in CPF into your long-term planning. You may be contributing to an SRS account, and therefore need to plan the withdrawals upon retirement age. These will be particularly important to plan if you wish to relocate and retire out of Singapore.

5. Consider Tax Implications

Tax regulations can be complex for expats, especially if you have income sources in multiple countries. Regularly review your tax situation to ensure compliance and optimise your tax liabilities. Work with a tax professional to understand any changes that may impact your financial goals, including tax treaties between Singapore and your home country. Also remember that you should consider the taxes in countries where you have assets, so if you’ve done a stint in another country before Singapore, other than your home country, it is wise to understand their tax rulings, too.

6. Set New Financial Goals

Once you have evaluated your financial position, living costs, investments, and tax implications, it’s time to set new financial goals. These might include saving for a home, funding your children’s education, or planning for retirement. Make sure your goals are SMART (Specific, Measurable, Achievable, Relevant, Time-bound) to ensure clarity and focus in your financial planning.

7. Stay Flexible and Seek Professional Advice

The expat experience can be unpredictable, and your financial goals may need to adapt accordingly. Stay flexible and be open to revisiting your plans regularly. Engaging a financial advisor who understands the unique challenges faced by expats in Singapore can provide valuable insights and help you navigate the complexities of financial planning. It would also be helpful if they can work with your tax advisor, to ensure that your financial & investment planning is tax efficient, and maximising your portfolio.

Living in Singapore as an expat can be a rewarding experience, but it also necessitates a proactive approach to financial management. By regularly reassessing and realigning your financial goals, you can navigate the challenges of expatriate life while securing your financial future. Remember, the key to successful financial planning lies in adaptability and informed decision-making.

How Can Expats Succeed Financially in 2025

It’s the start of a new year, and something that’s always on our to-do list is finances. Many want to start the year off right, by organising their finances to ensure a successful and fruitful year. But then, many get stuck, pondering on where to begin. Here are five ways expatriates in Singapore can achieve financial success in 2025!

1. Create a Budget

Every great plan has sturdy foundations. That’s why it’s essential to develop a comprehensive budget that reflects your income and expenses. It’s crucial to account for factors such as housing, schooling, and healthcare.

Establish a monthly budget that includes all your necessary expenses—rent, utilities, groceries, and transportation—while also allocating funds for savings and discretionary spending. This will help you identify unnecessary spending and make adjustments to ensure you stay within your budget. I like to use the 50/30/20 rule (50% on necessary expenses, 30% on lifestyle & 20% on savings & investments) as a starting point.

You can read more on how I budget here: https://danielleteboul.com/2021/02/08/how-i-planned-my-finances/

If you want to understand more about the cost of living in Singapore, I recently posted this article: https://danielleteboul.com/2024/09/02/understanding-singapores-cost-of-living-a-breakdown-for-new-expats/

2. Build an Emergency Fund

Life can be unpredictable, and having an emergency fund is essential for financial stability. Aim to set aside at least three to six months’ worth of living expenses in a high-yield savings account. This fund will act as a safety net in case of unexpected events such as job loss, medical emergencies, or urgent travel.

Establishing this fund will give you peace of mind and allow you to focus on long-term financial goals without the constant worry of financial insecurity.

To read more on how to be prepared for emergencies, check out this post: https://danielleteboul.com/2024/10/25/emergency-preparedness-financial-and-lifestyle-considerations-for-expats/

3. Open an SRS Account

 The SRS (Supplementary Retirement Scheme) is a voluntary savings scheme designed to encourage individuals to save for retirement while benefiting from tax concessions. Investing in an SRS account allows you to contribute up to SGD 15,300 (for Singaporeans and PRs) or SGD 35,700 (for foreigners) annually, depending on your residency status.

https://www.iras.gov.sg/taxes/individual-income-tax/basics-of-individual-income-tax/special-tax-schemes/srs-contributions

The contributions you make to your SRS account are eligible for tax relief, reducing your taxable income. Additionally, the funds in your SRS account can be invested in various financial instruments such as stocks, bonds, and mutual funds, giving you the potential for growth. I would strongly advise not leaving the money as cash within your SRS account, eroding against inflation and investing that money instead.

4. Invest Wisely

Following on from the previous point, investing is a key component of financial success. With the right approach, you can grow your wealth and prepare for the future. Consider your risk tolerance and consider diversifying your portfolio to mitigate potential losses. Understand your objectives, and remember that investing is for the long term, not just for the quick wins.

Seek advice from financial advisors to gain insights into the best practices for investing in Singapore.

If you’d like to learn more about long-term investment planning, such as retirement planning, check out this article: https://danielleteboul.com/2024/10/25/emergency-preparedness-financial-and-lifestyle-considerations-for-expats/

5. Stay Informed About Tax Regulations

As an expat, understanding Singapore’s tax regulations is vital to your financial success. Familiarise yourself with the tax obligations that apply to you, including income tax rates and any reliefs or exemptions available. Consulting with a tax advisor who specialises in expat taxation can help you navigate this complex landscape and ensure you meet all your obligations while maximising any potential benefits. Remember, take into consideration the tax in the country you live in, the tax rules of your home country, and the tax rules of any country you have assets in.

Achieving financial success as an expat in Singapore is attainable with the right strategies. By following these five simple tips, you can set yourself up for a prosperous year ahead. With careful planning and discipline, your financial future in Singapore can be bright and rewarding.

It’s very important to normalise talking about finances, especially as expats in Singapore, where information can be confusing and may not apply to us.